Bank on My Terms
The Art of BankCraft™
BankCraft Classroom
The Premium Membership Trap
Things Are Often Not as They Appear
Sometimes the biggest savings rate is not the best deal. Here’s one impressive-looking offer worth examining.
October 27, 2026 · By D.B. Nomad
Case in Point
Holy cow! 4.70% APY!
On savings up to $20,000! And all you have to do is upgrade to a Premium Savings Membership for just $10 a month. What's not to like?
Take a good look at this advertisement. It's designed to get your attention.
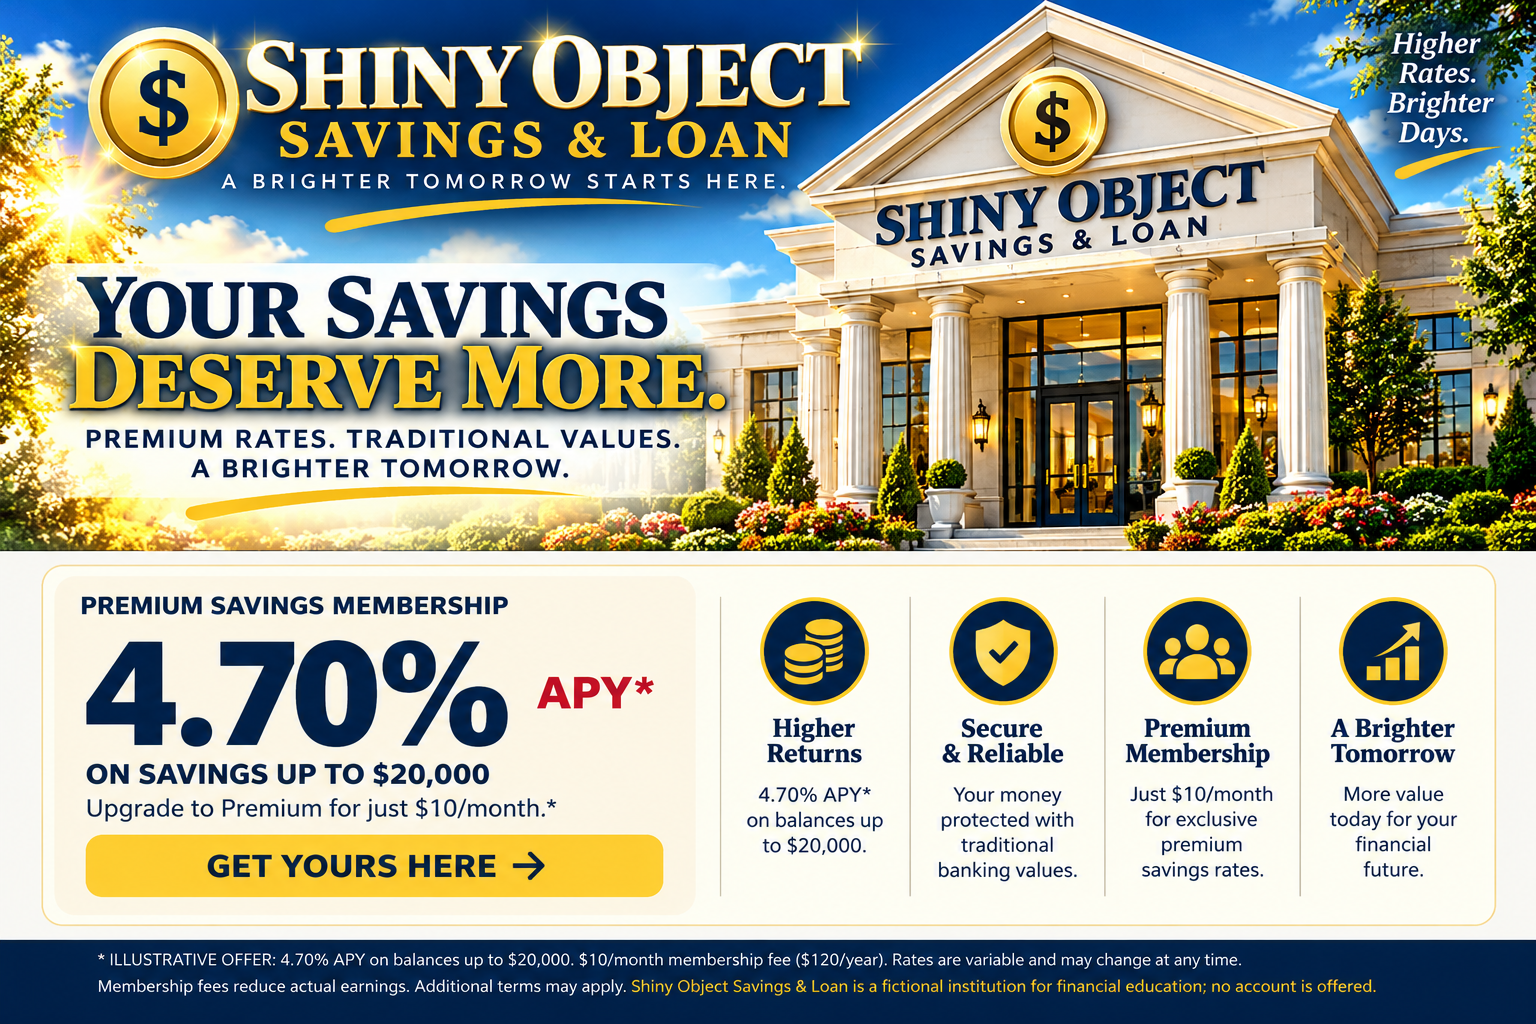
Looks impressive, doesn't it? A premium interest rate, a prestigious-looking institution, and a membership that promises more for your money.
But we haven't answered the only question that really matters: What will you actually keep?
Now, Here's the Truth
That “membership” is a fee.
It's $10 a month. That's $120 every year.
They didn't hide it. It's right there in plain sight. But the big, beautiful 4.70% is the shiny object. Before you pay to get that number, there's a simple question: How much of your interest do you actually keep after paying the membership fee?
Let's compare this fictional 4.70% membership account with another fictional savings account paying 4.25% APY with no monthly fee. Same deposit. Same year. Different amount in your pocket.
Look at the Pictures. Then Look at the Numbers.
Let's do the math.
We'll start with the full $20,000, then cut it down. Watch what that $120 annual membership does as your balance gets smaller.
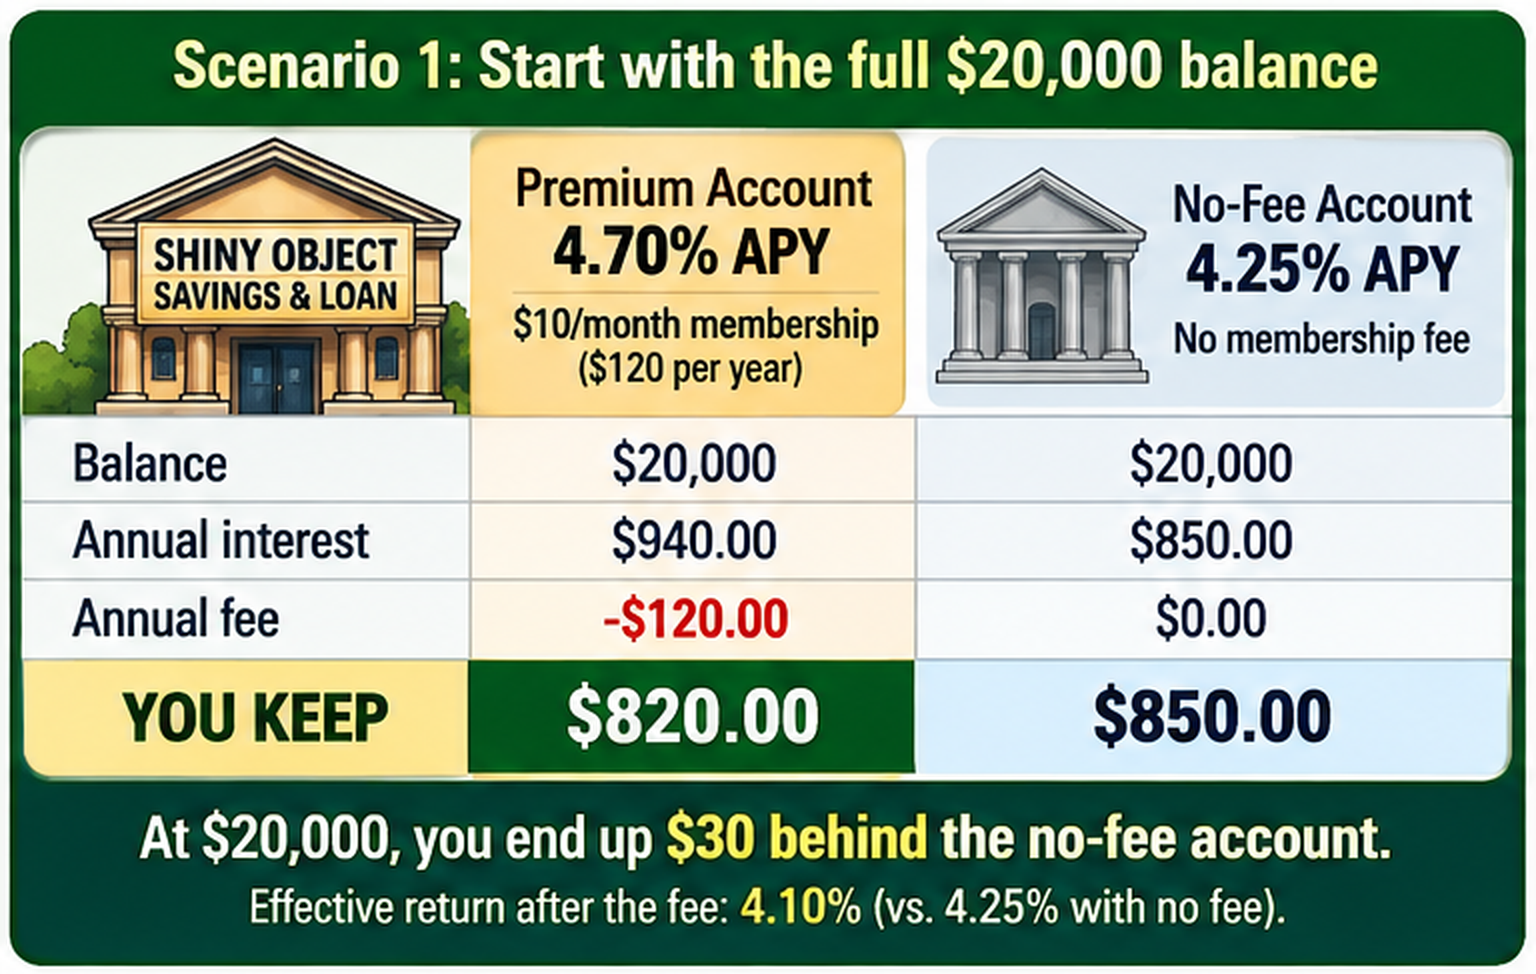
First, let's try $20,000.
You've deposited the entire $20,000 eligible for 4.70%. That's $940 in interest over a year. Nice!
But your Premium Savings Membership costs $120. You're left with $820. The ordinary 4.25% account earns $850 without charging admission.
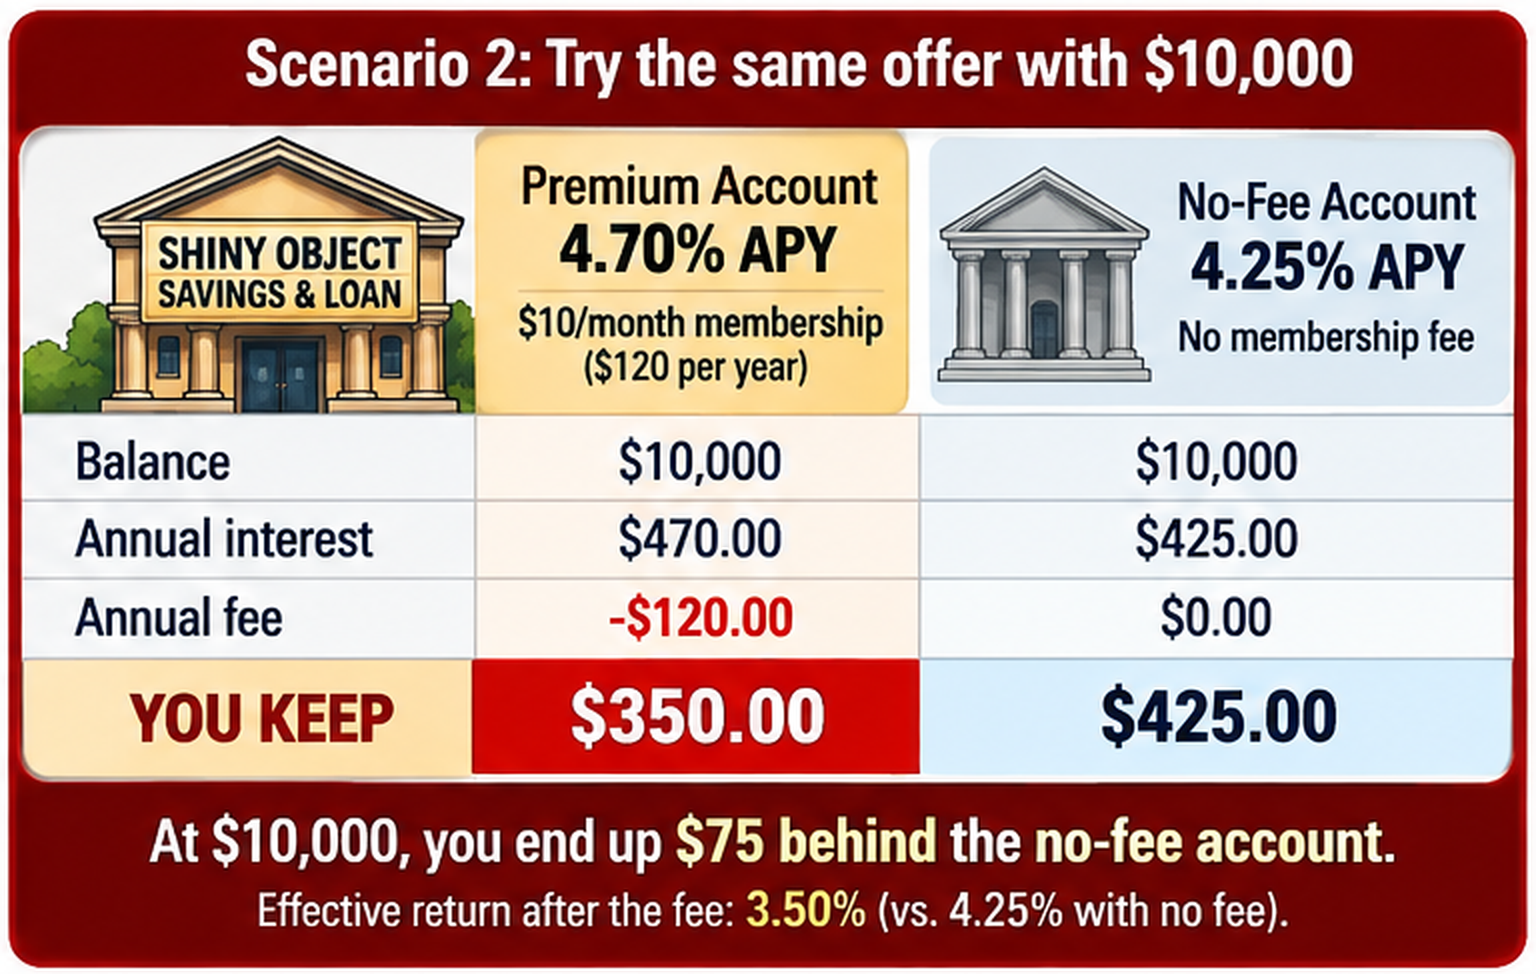
Now, cut that in half. $10,000.
Same 4.70% headline. Same $10 monthly membership. But now you've earned $470 in interest and handed back $120 just to belong to the club.
You keep $350. The 4.25% no-fee account earns $425.
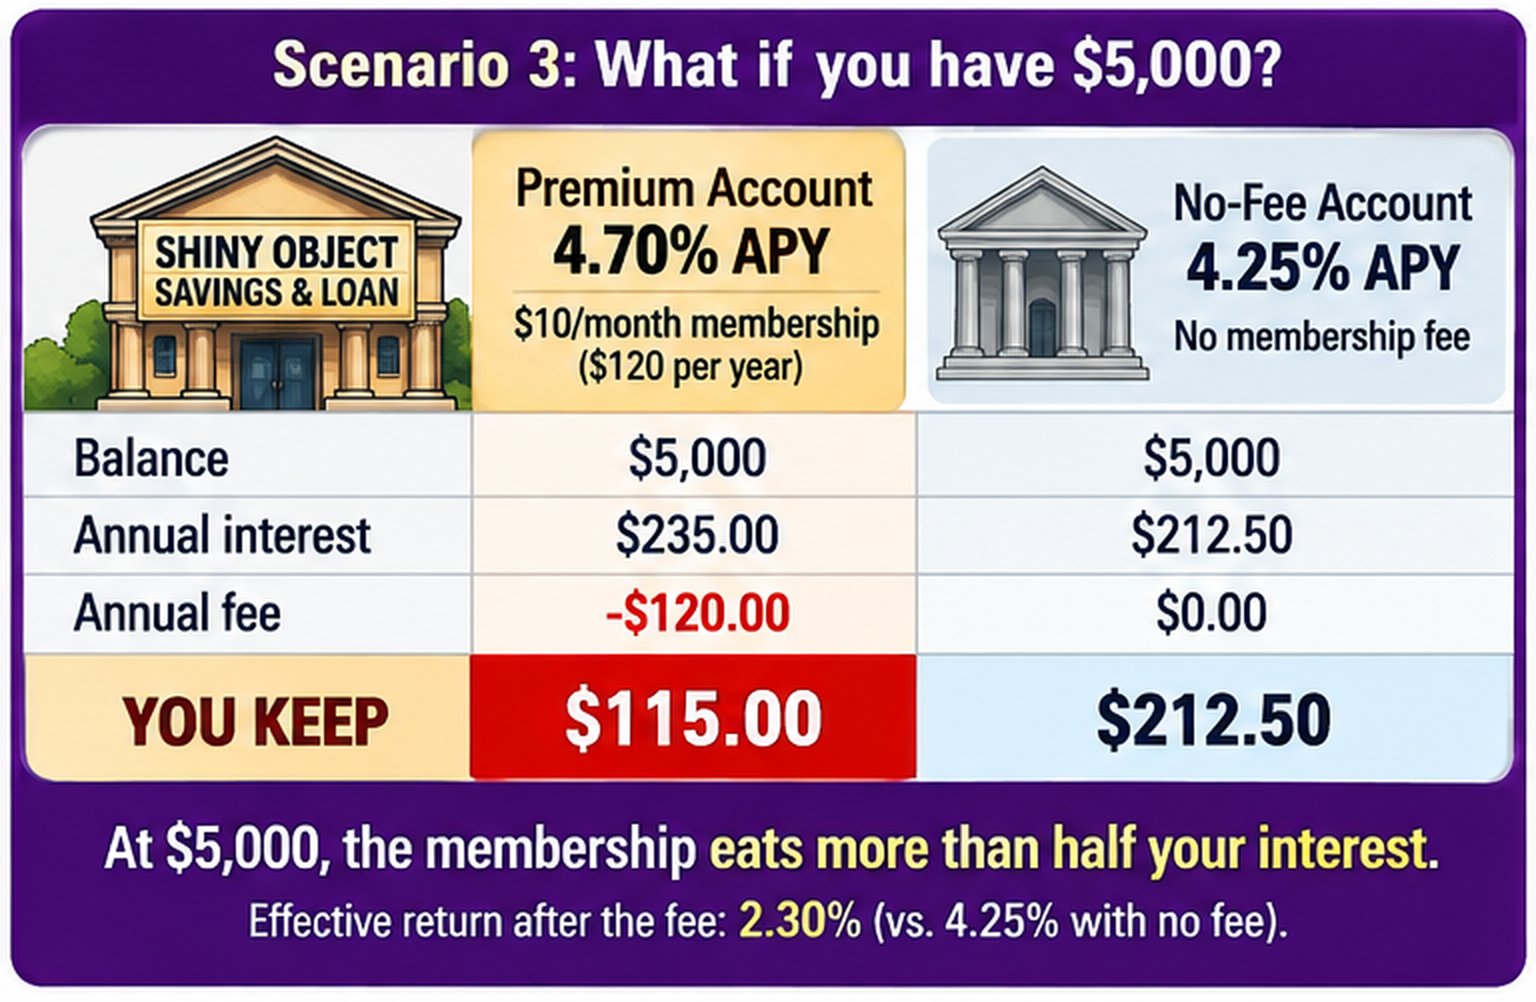
How about $5,000?
Maybe that's what you've worked hard to save. Naturally, you want every dollar earning as much as possible.
Your 4.70% earns $235, but that $120 membership leaves you only $115. The no-fee account earns $212.50.
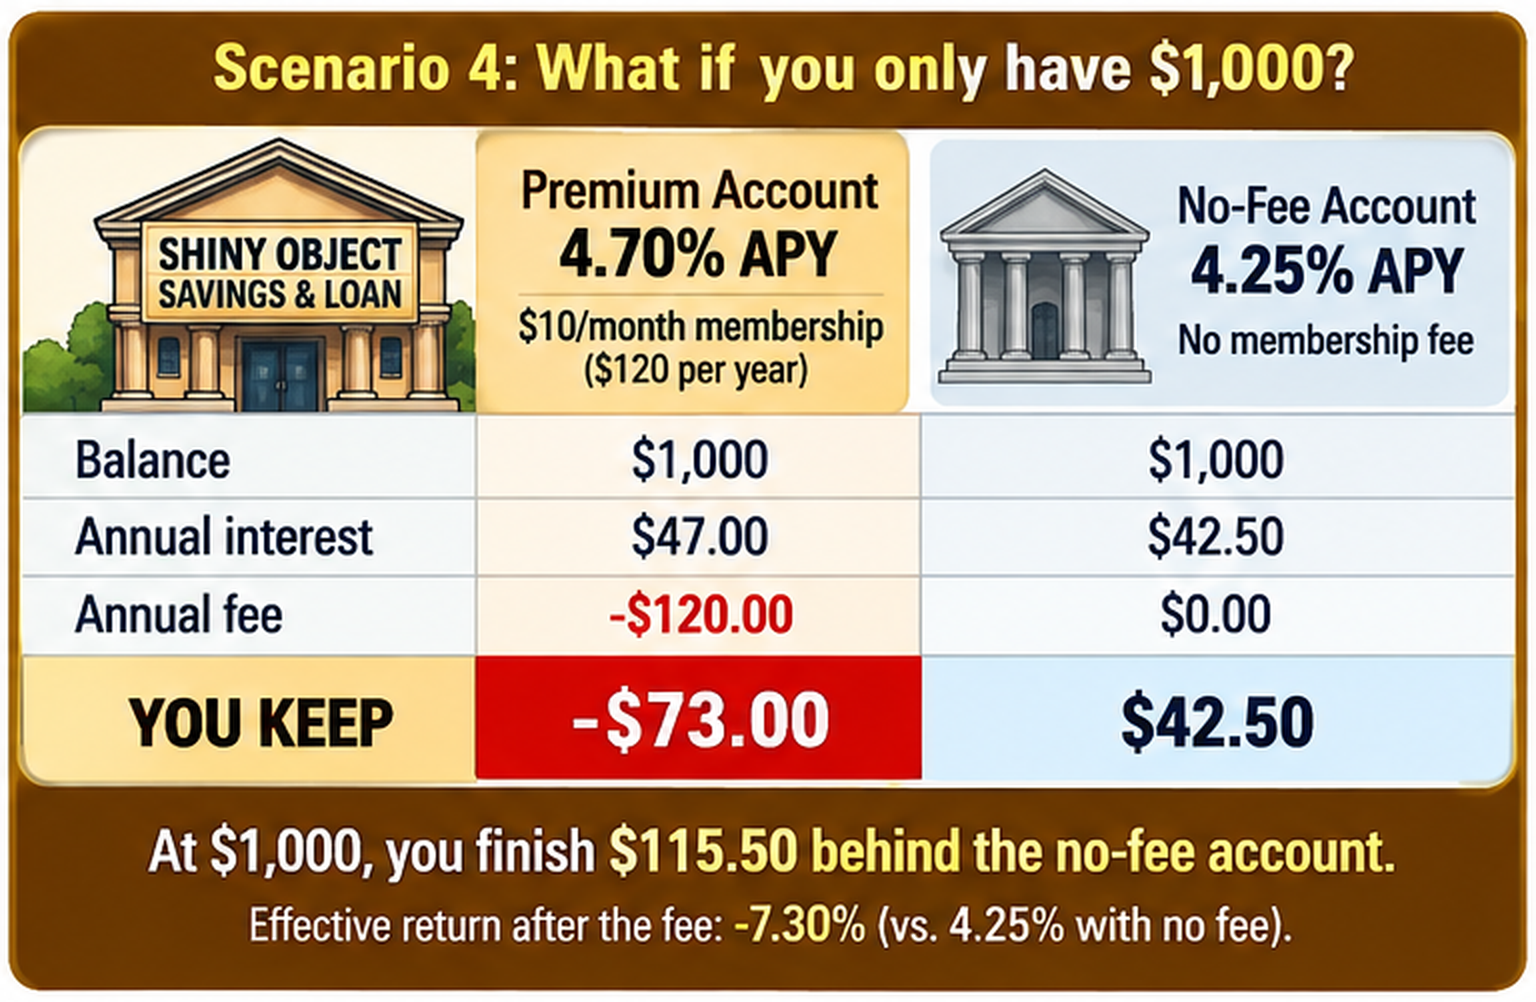
And if all you've got is $1,000?
Here's where the wheels come off the wagon. You earned $47 in interest. You paid $120 for the membership.
Now you're down $73 for the year! Meanwhile, the plain old 4.25% account would have earned you $42.50.
Don't Put the Blinders On
All you saw was 4.70%, didn't you?
Think of a mule plowing a field with blinders on. Straight ahead. Nothing to the left, nothing to the right.
That's what can happen when we shop for an interest rate. We see 4.70% APY! Holy cow, I want some of that! And we keep looking at that number while barely giving the membership another thought.
After all, everybody has memberships. What's another $10 a month?
Here's the trick: The advertised APY can be accurate, the membership price can be disclosed, and the savings deal can still leave you with less money than a lower-rate alternative.
The advertisement gets your attention. The arithmetic tells you whether it deserves your money.
It reminds me of the county fair. The giant stuffed animal gets your attention from across the midway. But before you put down your money, wouldn't you want to know what the game costs and what your chances really are?
A savings account shouldn't require guesswork. Don't let an impressive number separate you from your money.
Inspired by a Real Advertisement
You think we just dreamed this up?
On October 27, 2026, we came across a real savings promotion advertising 4.70% APY on balances up to $20,000 through a $10-per-month premium membership. The membership cost was in the promotion itself, in plain sight.
That inspired our fictional Shiny Object Savings & Loan example. We aren't saying the real membership has no other benefits; those benefits may be valuable to some customers. We're showing you how to test the savings return when a membership has a price.
Do the math for your own balance, and ask whether the other membership benefits are genuinely worth the cost to you.
BankCraft Protocol: Membership AKA Fee
1. Start with your balance. Not the maximum balance in the advertisement—your actual savings.
2. Calculate the interest. Use the APY and make sure you understand any cap or tier.
3. Subtract what you pay. A monthly membership is still a cost, whatever it's called.
4. Compare what you keep. Then decide whether any additional membership benefits justify the price.
Trust the Process! Do the Math!